
Voluntary Delisting Prices: Share Prices Alone Are No Longer Enough
2026-09-15
One tool controlling shareholders often use to turn a company into a wholly owned subsidiary is a “comprehensive share exchange.” For example, if a parent company already owns 90% of a subsidiary’s shares, it can acquire all the shares held by shareholders owning the remaining 10% through a special resolution at a shareholders’ meeting, even without those shareholders’ individual consent.
A comprehensive share exchange ordinarily involves giving shares in the parent company to shareholders holding the remaining 10% of the subsidiary, but the Commercial Act also allows cash to be paid instead. If the parent company pays these shareholders cash rather than its own shares, minority shareholders must surrender their shares and receive cash regardless of their wishes. This is known as a “cash-out comprehensive share exchange.”
Recently, companies have frequently used tender offers to acquire a stake, followed by a comprehensive share exchange to squeeze out the remaining shareholders and delist. However, an amendment to the Capital Markets Act recently passed by the National Assembly on August 30, 2026, is set to significantly change the most important part of this process: how the price is determined.
Until now, “market price” has been a key benchmark
In comprehensive share exchanges involving listed companies, recent stock market prices have served as a key benchmark for determining the share exchange price. At first glance, this seems reasonable because listed shares have a market price every day.
But share prices do not always reflect a company’s actual value. Many companies hold substantial assets, such as cash and real estate, yet trade far below their net asset value. Others generate steady profits but remain undervalued for years because of insufficient dividends or share buybacks.
For example, suppose a company’s shares trade at 10,000 won, but its net asset value is 18,000 won per share and its value based on future earnings is 22,000 won per share. If minority shareholders’ shares are acquired for around 10,000 won based solely on the market price, shareholders will naturally question this.
The question is: “If the company’s actual value is higher, why should I have to exit at today’s low share price?”
Under the amended Capital Markets Act, asset value and earnings-based value must now be considered alongside share prices
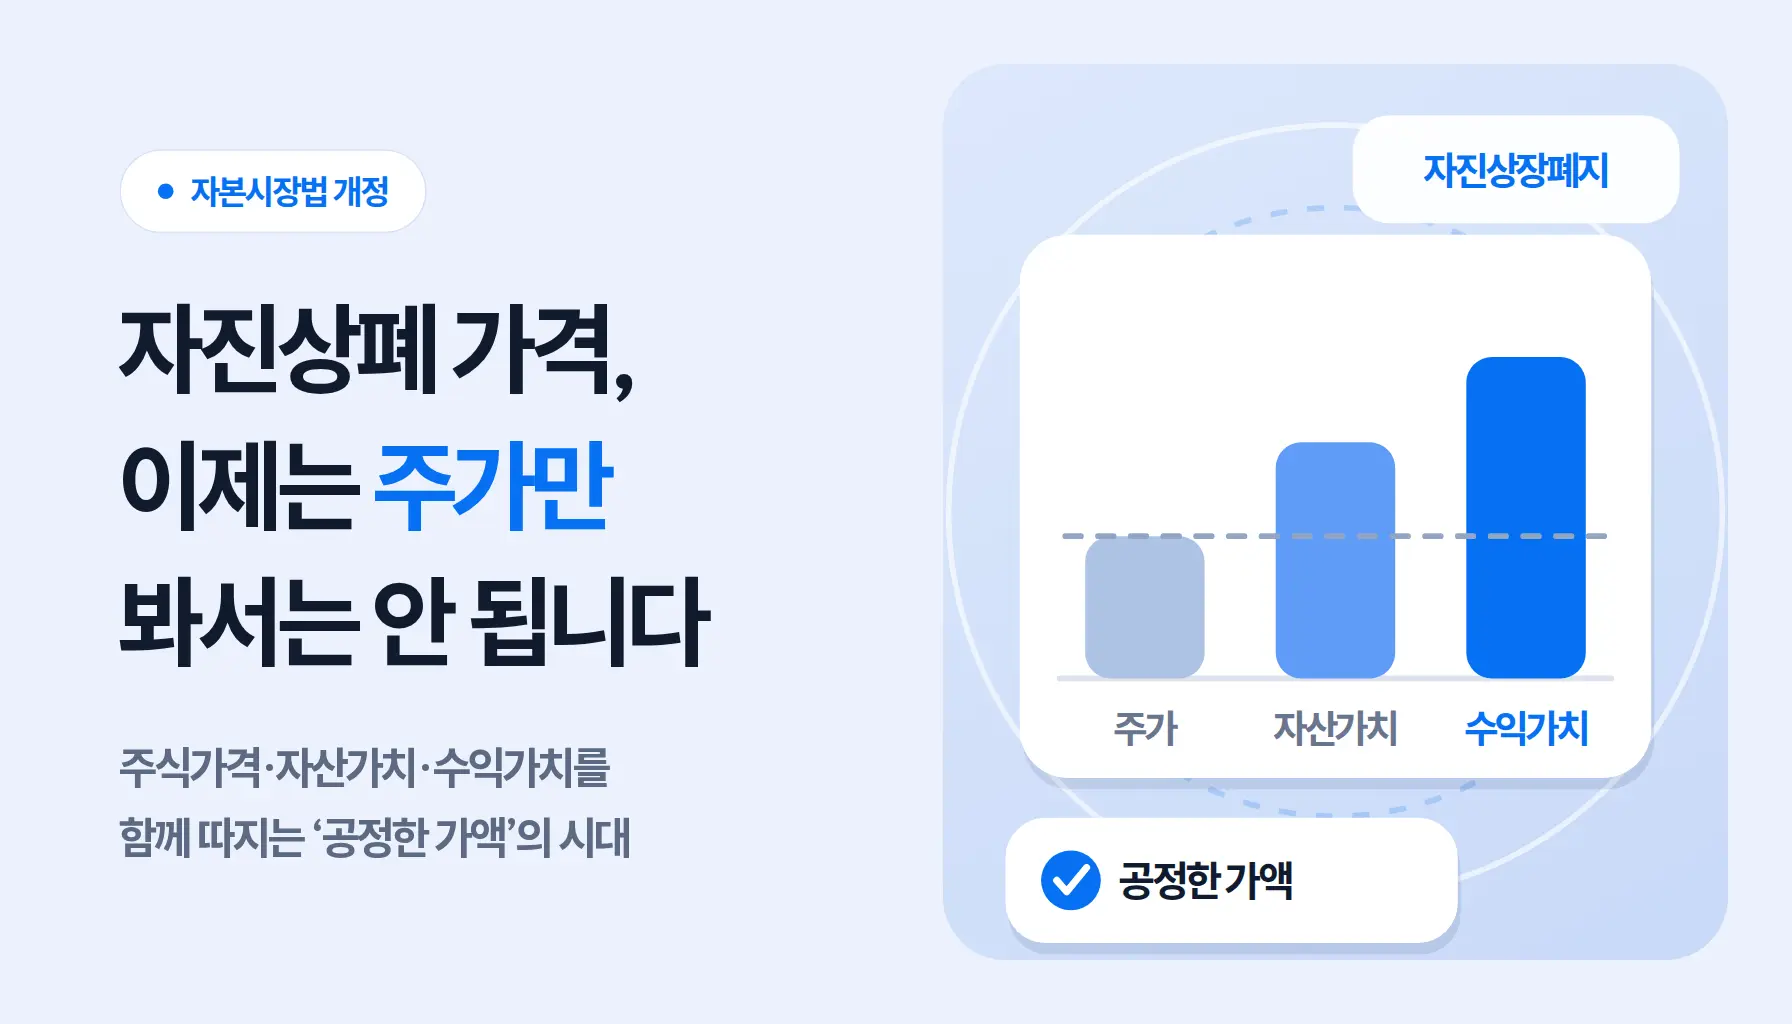
The core of this amendment to the Capital Markets Act is the requirement to determine a “fair price” for comprehensive share exchanges by considering share prices, asset value, earnings-based value, and other factors together, rather than relying solely on market prices.
Asset value means the value of a company’s net assets, including cash, real estate, and investment assets, after deducting liabilities. Earnings-based value is the present value of the profits and cash flows the company will generate in the future. This includes methods such as DCF, which is widely used in company valuation.
Going forward, it will no longer be enough to ask only, “What has the share price been recently?” We must also consider: “How much are the assets the company actually holds worth?”, “How much profit can it generate in the future?”, and “How does its valuation compare with similar companies?”
This is particularly significant for companies with low price-to-book ratios (PBRs). If a company’s net asset value is 10,000 won per share but its shares trade at 4,000 won, simply saying, “The share price is 4,000 won, so a price around that level is sufficient,” may no longer be enough. It will be necessary to explain why acquiring shares at a price far below their net asset value of 10,000 won is fair.
Voluntary delisting strategies following tender offers are also expected to be affected
Recently, voluntary delistings have often combined tender offers with comprehensive share exchanges.
For example, suppose a controlling shareholder makes a tender offer of 10,000 won for a company whose shares trade at 8,000 won, and a substantial number of shareholders accept. Once a sufficient stake has been acquired, the controlling shareholder can carry out a cash-out comprehensive share exchange for the remaining minority shareholders, make the company a wholly owned subsidiary, and then delist it.
The problem is that, under the current Capital Markets Act, the tender offer price can effectively become the benchmark for the subsequent comprehensive share exchange price. This can create a structure in which the controlling shareholder who initially set the tender offer price ultimately also determines the price at which the remaining minority shareholders are forced out.
After the amendment, it will be harder to argue that a comprehensive share exchange price of 10,000 won is sufficient simply because the tender offer price was 10,000 won. If the company’s net asset value or earnings-based value is higher, a separate explanation and valuation will be needed to establish why that price is fair.
However, cash-out comprehensive share exchanges themselves are not being prohibited. If the controlling shareholder meets the requirements for a special resolution at a shareholders’ meeting, it will still be possible to transfer the shares of dissenting minority shareholders. The purpose of this amendment is not to allow minority shareholders to remain shareholders if they wish, but to ensure that they receive a fairer price when they are forced out.
It now matters not only what the price is, but also who performed the valuation and how
This amendment strengthens not only the pricing methodology but also the procedures. A board of directors deciding on a comprehensive share exchange must prepare and disclose its opinion on matters including the transaction’s purpose and expected benefits, as well as the appropriateness of the share exchange price.
Simply explaining, “The price is appropriate because an external firm performed the valuation,” may therefore not be enough. The board must explain for itself why the transaction is necessary for the company and its shareholders, and why the price is fair.
The independence of external valuations will also become more important. In particular, safeguards to increase the independence of valuation procedures in transactions between affiliated companies will be strengthened, including requiring the statutory auditor or audit committee to select the external valuation firm.
The approach to determining the share purchase price for dissenting shareholders exercising their appraisal rights will also shift toward considering not only market prices but also asset value and earnings-based value. In future disputes, “What is the company actually worth?” is likely to become a more important issue than “What is the current share price?”
Shareholders should now focus on “fair value,” not the “premium”
Going forward, shareholders should be especially wary of statements such as, “We have offered a price 30% above the current share price.”
A price 30% above the share price may sound like a substantial premium. But the picture changes if the company’s net asset value is twice its current share price. A high premium over the market price does not, by itself, make that price fair.
However, a net asset value of 20,000 won per share does not necessarily mean that at least 20,000 won must be paid. During deliberations in the National Assembly, a proposal to require the share exchange price to be at least the net asset value was discussed, but it was not included in the final amendment. How asset value and earnings-based value should be assessed, and how much weight each should receive, will remain important issues.
Nevertheless, the direction is clear. It will become harder than before to use a persistently undervalued market price, unchanged, as the price at which minority shareholders are forced out.
Therefore, when a voluntary delisting or comprehensive share exchange is announced, the first question shareholders should ask is not, “How much more than the share price are we being offered?” They must also examine the company’s net asset value, its earnings-based value considering future profits and cash flows, how the external valuation firm calculated the price, and why the board judged that price to be fair.
Ultimately, it comes down to one question.
“Does this price really reflect the company’s value accurately?”
This is where shareholders’ questions about comprehensive share exchanges and voluntary delistings should begin from now on.